Quarterly estimated taxes: a 2026 guide for the self‑employed

 Sarah York, EASarah is an Enrolled Agent with the IRS and a former staff writer at Keeper. In 2022, she was named one of CPA Practice Advisor’s 20 Under 40 Top Influencers in the field of accounting. Her work has been featured in Business Insider, Money Under 30, Best Life, GOBankingRates, and Shopify. Sarah has spent nearly a decade in public accounting and has extensive experience offering strategic tax planning at the state and federal levels. Her clients have come from a wide range of industries, including oil and gas, manufacturing, real estate, wholesale and retail, finance, and ecommerce, and she has handled tax returns for C corps, S corps, partnerships, nonprofits, and sole proprietorships. In her spare time, she is a devoted cat mom and enjoys hiking, painting, and overwatering her houseplants.
 Reviewed byScott LevyScott Levy grew up in Miami, Florida, the son of a CPA and Tax Attorney. You could say taxes were in his blood. He's been a licensed CPA since 2011 with a Bachelors in Accounting, and a Master's in Applied Economics and Data Intelligence. Over the years, Scott has worked with a large variety of clients from different walks of life. From bartenders to CEOs, Scott has helped them all maximize their tax savings and plan for their futures.
 Krislyn ChanKrislyn is Chief Growth Officer at Keeper. At Keeper, she strives to make expert-level tax strategies that used to require a traditional CPA accessible to all. Prior to Keeper, she was at Curology, where she helped bring custom, prescription-grade skincare out of the dermatologist's office to millions of faces.

Key takeaways
- Who has to pay: You generally need to make estimated payments if you expect to owe $1,000 or more for 2026 after withholding and credits. That covers most freelancers, 1099 contractors, and gig workers.
- 2026 due dates: April 15, 2026; June 15, 2026; September 15, 2026; and January 15, 2027.
- How to pay: Schedule your payments in Keeper, or pay the IRS directly through Direct Pay, your IRS Online Account, the IRS app, a card processor by phone, or extra W-2 withholding.
- How to avoid a penalty: Pay at least 90% of your 2026 tax or 100% of your 2025 tax (110% if your 2025 AGI was over $150,000) through withholding and estimated payments.
- What you’re paying: Self-employment tax of 15.3% on 92.35% of your net earnings, plus federal income tax and, in most states, state estimated payments.
Understand your estimate
Your estimated tax bill and the amount you need to pay during the year can be different. Your income estimate helps you plan for the total bill. Safe-harbor rules help determine how much to pay on time to generally avoid a federal underpayment penalty.
Before using the result to make a payment, check the income period, business expenses, withholding, and estimated payments you have already made. Federal and state payments go to different tax agencies.
When are quarterly taxes due in 2026?
The general federal estimated-tax deadlines for the 2026 tax year are April 15, June 15, September 15, and January 15, 2027. The payment periods are not four equal calendar quarters.
| Payment | Income period | Due date |
|---|---|---|
| 1st | January 1 to March 31, 2026 | April 15, 2026 |
| 2nd | April 1 to May 31, 2026 | June 15, 2026 |
| 3rd | June 1 to August 31, 2026 | September 15, 2026 |
| 4th | September 1 to December 31, 2026 | January 15, 2027 |
State deadlines and special federal rules can differ. Check out your state’s requirements here. Check for applicable disaster relief.
How to use the quarterly tax calculator
Use expected amounts for the full tax year. For income you have already earned, add a reasonable estimate of what you expect to earn before December 31.
| Input | What to include |
|---|---|
| Tax filing status | The status you expect to use on this year’s return. If you choose married filing jointly, you’ll also enter your spouse’s income. |
| State | The state for the estimate. Working or living in more than one state may require separate calculations. |
| Employment income (W-2) | Expected taxable wages from employment for the full year. |
| Freelance / business / 1099 income | Your expected business profit: receipts from freelance or business work minus the business portion of deductible expenses. |
| W-2 taxes withheld (under “Add advanced info”) | Expected full-year federal income tax withheld from your paychecks. Use pay records when available. If you leave it blank, the calculator assumes standard withholding. |
| Student tuition, mortgage interest, traditional IRA contributions (optional) | Full-year amounts, only if they apply to you. |
For example, a freelance designer expecting $90,000 in client payments and $15,000 in deductible expenses has $75,000 in business profit. Enter $75,000 as freelance / business / 1099 income.
The calculator estimates your full-year payments. It doesn’t ask for estimated payments you’ve already made, so subtract those before you pay.
What the calculator handles for you
- Your standard deduction for 2026: $16,100 single, $32,200 married filing jointly, and $24,150 head of household. You can still deduct business expenses on top.
- The QBI deduction, which generally lets you deduct up to 20% of your business profit. The calculator applies the main limits but can’t cover every scenario. Learn more about the qualified business income deduction.
- Self-employment tax on your business profit.
- Your state’s rules: whether you meet the state’s threshold for estimated state payments, and how the total splits into installments, including uneven schedules like California’s.
What it doesn’t include
- Your business deductions. Subtract them before you enter your business income. Not sure what you can write off? Keeper finds them for you.
- Most tax credits, such as child or education credits. If you qualify for credits, the estimate may be high, so you could overpay and get the difference back as a refund. Last year’s return lists the credits you received (see Schedule 3).
Track and claim every eligible deduction with Keeper
The #1 tax app for freelancers, gig workers, and self-employed filers.
Get started free

Do you need to make estimated tax payments?
For 2026, you generally need federal estimated payments if you expect to owe at least $1,000 after subtracting withholding and refundable credits.
However, if your withholding and refundable credits are at least 100% of your prior-year tax (or 110% if your prior-year AGI was above $150,000), then you have met the “safe harbor” amount (see below) and are not required to make estimated payments. Having 1099 income doesn’t settle the question.
A W-2 job can change the answer: sufficient paycheck withholding may cover the tax on your freelance work too. Your state may use a different threshold.
If you had no federal tax liability for all of 2025 and were a US citizen or resident alien throughout that year, you generally do not need 2026 federal estimated payments. A refund or a zero balance due does not necessarily mean you had zero tax liability. See 2026 Form 1040-ES.
What taxes are included in a quarterly estimate?
Federal estimated payments can cover both income tax and self-employment tax. They are prepayments toward your annual taxes, rather than a separate tax added to your return.
Income tax depends on your household income, filing status, deductions, and credits. That is why two freelancers with the same business profit may owe different amounts.
Self-employment tax pays toward Social Security and Medicare. The usual combined rate is 15.3%, generally applied to 92.35% of net self-employment earnings. The Social Security portion has an annual earnings limit, and W-2 Social Security wages count toward it. Medicare follows different rules, including an additional tax for some higher earners.
State taxes are separate. A federal estimate does not determine what you must pay your state.
Safe harbor versus your final tax bill: what’s the difference?
A federal safe harbor is a payment threshold that generally helps you avoid an underpayment penalty when you meet the installment deadlines. It does not reduce the total tax you owe.
The general annual target is the smaller of 90% of your 2026 tax or 100% of your 2025 tax. The prior-year percentage becomes 110% if your 2025 adjusted gross income exceeded $150,000, or $75,000 if you file married filing separately for 2026. The prior-year return must cover 12 months. Special rules apply to some taxpayers. Source: Form 1040-ES.
Example: a consultant whose income increased
Assume a consultant expects $24,000 of total federal tax for 2026, had $18,000 of relevant prior-year tax, qualifies for the 100% prior-year rule, and has no withholding or credits affecting this simplified example.
| Calculation | Amount |
|---|---|
| 90% of expected 2026 tax | $21,600 |
| 100% of prior-year tax | $18,000 |
| Smaller annual payment target | $18,000 |
| Four equal timely installments under the regular method | $4,500 each |
| Potential balance when filing, if total tax is $24,000 | $6,000 |
What if your income changes during the year?
Update your estimate when a major client starts or leaves, your expenses change, or you earn a large one-time payment. A full-year estimate made in April can become inaccurate by September.
If income arrives unevenly, the annualized income installment method may produce different required payments. It uses income and deductions through specified periods; it is not simply the year’s tax divided by four. Read Keeper’s guide to annualizing income and the IRS instructions.
What if you already missed a payment?
Pay what you owe as soon as you can. Don’t wait for the next due date to catch up. The IRS penalty works like interest: it’s charged on the amount you underpaid for each day it stays unpaid, so paying sooner keeps it smaller. Making a bigger payment next quarter doesn’t erase an earlier shortfall.
To see roughly what a late or short payment could cost, use Keeper’s estimated tax penalty calculator. For next steps, read our guide on what to do after missing a quarterly payment. If your income was uneven, the annualized method or a penalty exception may lower what you owe; see the IRS’s underpayment penalty guidance.
How to pay your estimated taxes
Let Keeper help you plan and pay your federal estimated tax payments
Upload last year’s return, wherever you filed, or enter your tax information in Keeper. Keeper calculates federal safe-harbor payments and lets you review and schedule them. State estimated payments are handled separately. See how Keeper’s quarterly payments work.
You can also pay the IRS directly. There are five ways to make estimated tax payments on your 1099 income:
Option #1: Direct Pay
Best if: You want to avoid making an account
If you want to make your federal payments yourself, IRS Direct Pay is a lightweight option. It doesn’t require you to set up an account or register in any way. You can simply:
- Input your tax details
- Make a payment
This is the easiest option: a direct debit from your bank account with no fees. But the IRS can also work with third-party merchants to handle credit card payments.
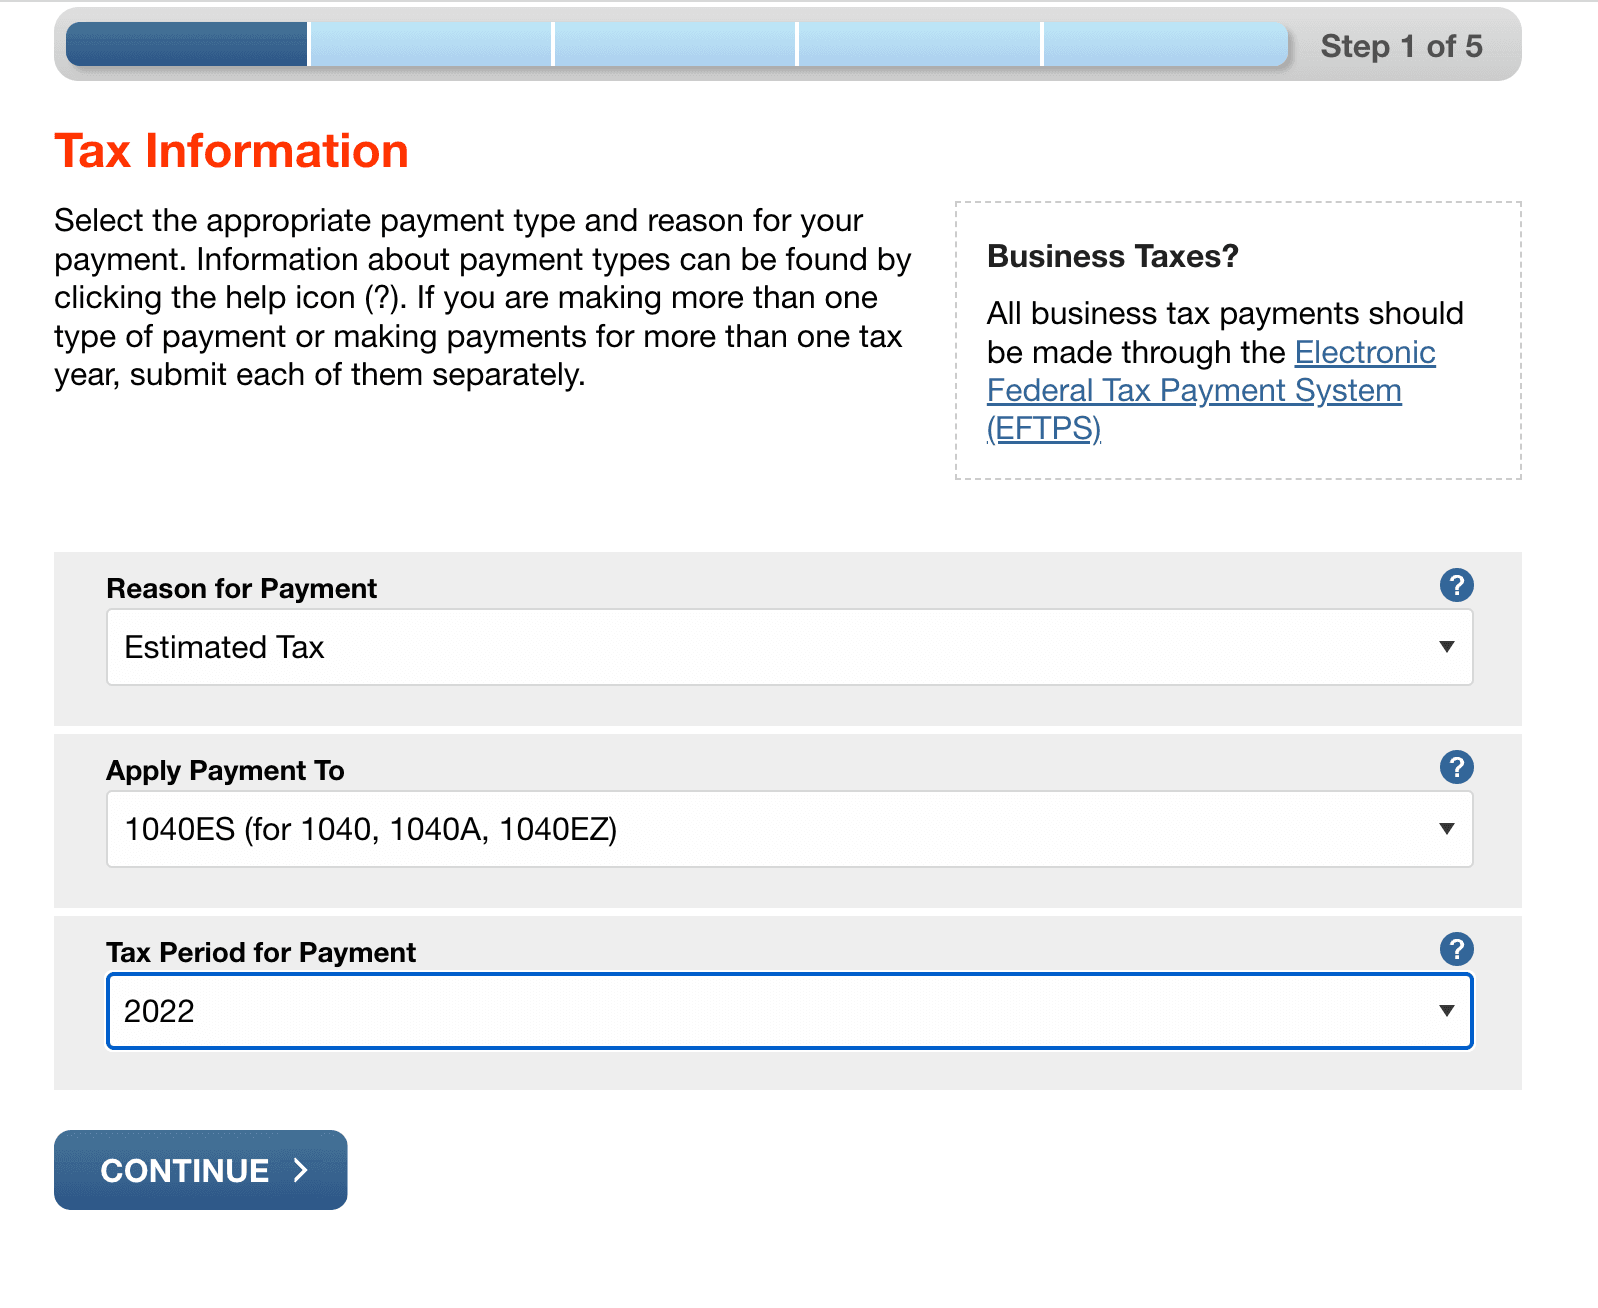
Option #2: An IRS online account
Best if: You might want to see your tax transcripts someday
You’ll need to set up an account to use this payment method, but I recommend all taxpayers do that at some point anyway. Having an account is the only way to easily view your tax records and transcripts on the IRS site, which is useful if you ever fall behind on your taxes and need to file them a few years late. It also lets you conveniently make estimated tax payments.
Option #3: Mobile app
Best if: You want to pay from your phone
In September 2026, the IRS retired IRS2Go and replaced it with a new app, simply called the IRS app, available for iPhone and Android. It’s built on your IRS Online Account, so once you sign in you can make a payment, check your balance and payment history, and pull up transcripts. If you still had IRS2Go installed, it should have updated to the new app automatically.
Option #4: Phone payments
Best if: You don’t want to deal with screens at all
You can also pay your estimated quarterly taxes by phone, but you won’t call the IRS. Instead, you’ll call one of the third-party providers listed below.
They’ll allow you to pay using credit, debit, or, in a few cases, an app. Either way, you’ll pay a convenience fee.
| Platform | Phone Number | Website | Credit Fee | Debit Fee |
|---|---|---|---|---|
| Pay1040 | 888-PAY-1040 | www.PAY1040.com | 1.87% ($2.50 minimum) | $2.50 |
| ACI Payments | 888-UPAY-TAX | fed.acipayonline.com | 1.85% ($2.50 minimum) | $2.50 |
Which third-party provider is best?
Each option comes with pros and cons:
- Pay1040 (formerly known as Link2Gov) offers the most payment methods, including PayPal
- ACI Payments is the only option to accept Venmo
Option #5: Increasing your W-2 withholding
Best if: You’re a side hustler who doesn’t mind doing extra paperwork
Last but not least, if you work a W-2 job in addition to your freelance work, ask your employer to increase your withholding by giving them an updated Form W-4. This saves you from having to submit payments yourself.
For example, if the results from this calculator tell you to pay $1,200 quarterly, have your employer increase your withholding by $200 on your twice-monthly payroll. This amounts to $400 a month, or $1,200 a quarter, all without you having to do anything. Bonus: the IRS treats withholding as if it were paid evenly through the year, no matter when it actually comes out of your check, so bumping up withholding late in the year can even make up for an estimated payment you missed earlier.
And with that, you’re off to the races! Be sure to visit Keeper’s Free Resources page for more tips and free tools, or download our app so that we’re never further than a click away.
Do state estimated taxes work the same way?
State thresholds and installment schedules can differ from federal rules. For example, California’s regular estimated-payment schedule is 30%, 40%, 0%, and 30%, rather than four equal payments. The 0% third installment is part of that schedule; it does not excuse earlier unpaid amounts. Source: California Franchise Tax Board.
Find your state’s estimated-tax rules, or choose a state below.
 By Soo Lee, CPA